Artificial intelligence in modern financial markets is not a monolithic technology, but a sophisticated ecosystem of mathematical models and algorithmic methods. In 2026, quantitative researchers and institutional hedge funds deploy diverse AI techniques for stock market analysis to ingest massive multi-asset data streams, identify non-linear market patterns, decode unstructured sentiment, and calibrate probabilistic risk models.
Among the most transformative methodologies driving modern quantitative finance are supervised machine learning, deep neural networks, recurrent architectures, natural language processing (NLP), and multi-horizon time-series forecasting. While these technologies provide unparalleled computational power, their mathematical sophistication does not guarantee infallible price predictions: financial markets remain non-stationary adaptive systems influenced by macroeconomic shocks, shifting liquidity regimes, and unpredictable human behavior.
This comprehensive guide examines the primary AI techniques for stock market analysis, evaluating their practical implementation architectures, comparative advantages, operational trade-offs, and essential model validation frameworks.
Core AI Techniques for Stock Market Analysis
Modern quantitative pipelines integrate multiple algorithmic paradigms depending on data structure, prediction horizon, and latency requirements. Below are the primary technical methodologies deployed across institutional research desks.
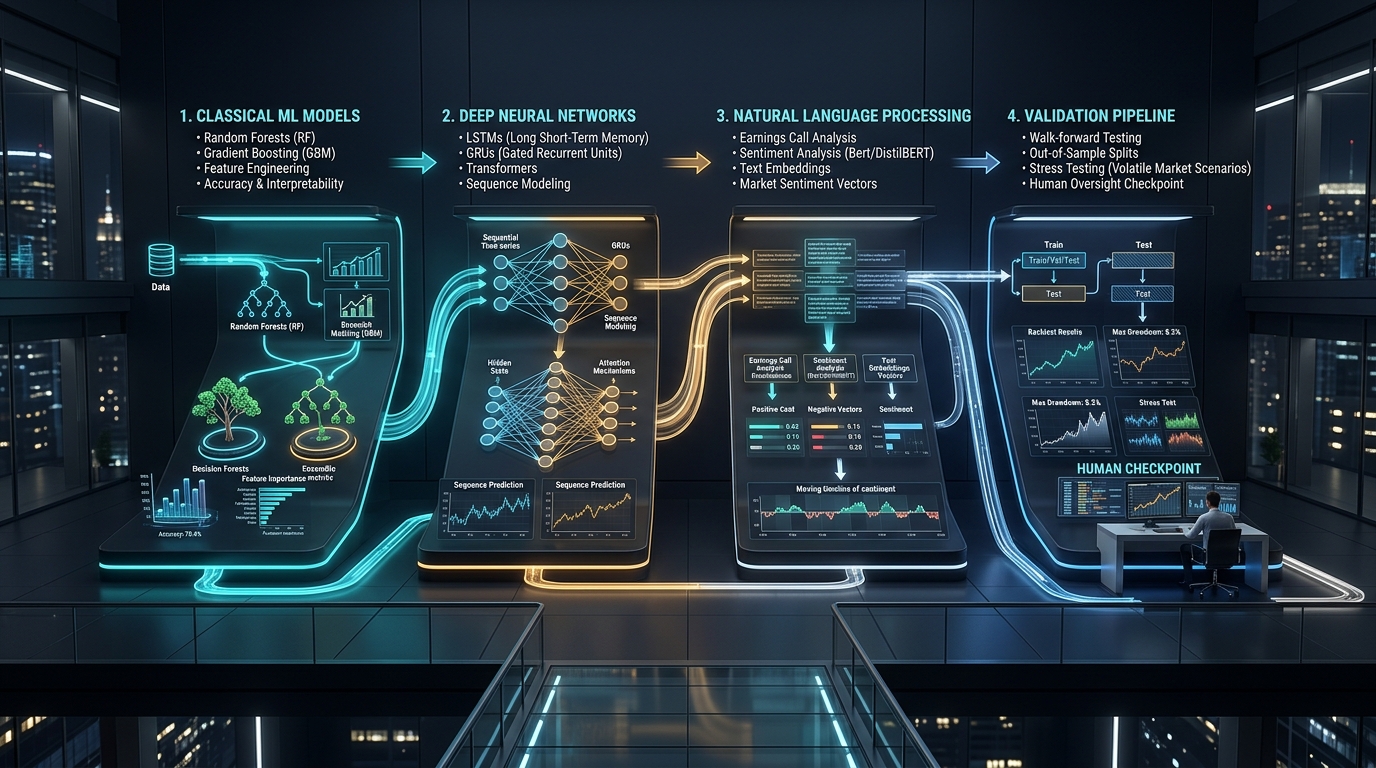
1. Supervised and Classical Machine Learning
Classical machine learning enables algorithmic systems to extract statistical relationships from tabular financial features rather than relying on hand-crafted heuristic rules. In institutional research, supervised algorithms excel across several core tasks:
- Cross-Sectional Classification: Ranking equities into expected outperformers and underperformers based on fundamental valuation ratios.
- Volatility & Spread Forecasting: Estimating intraday bid-ask spread expansion and realized volatility.
- Market-Regime Identification: Segmenting historical market phases into low-volatility trend, high-volatility mean-reversion, or liquidity squeeze regimes.
- Quantitative Feature Importance: Determining which economic variables (e.g., yield-curve inversion, credit spreads) exert the greatest predictive weight.
Commonly applied algorithms include Gradient-Boosted Decision Trees (such as XGBoost, LightGBM, and CatBoost) and Random Forests. These ensemble methods remain industry standards for tabular financial datasets because they handle missing data gracefully, resist overfitting better than unconstrained deep networks, and offer superior feature interpretability.
2. Feedforward Artificial Neural Networks (ANNs)
Artificial neural networks consist of interconnected computational nodes (neurons) organized into input, hidden, and output layers. Unlike linear econometric models (such as OLS regression or ARIMA), neural networks utilize non-linear activation functions (ReLU, GELU, Swish) to model intricate, non-linear interactions across macroeconomic and technical variables.
In quantitative workflows, feedforward networks map complex multidimensional feature vectors to continuous target returns or discrete probability distributions. However, because multi-layer networks possess millions of learnable parameters, they require rigorous regularization (dropout, weight decay, batch normalization) to prevent memorizing historical market noise.
3. Deep Learning Architectures
Deep learning extends classical neural networks through deep, hierarchical architectures capable of learning representations directly from raw financial data without exhaustive manual feature engineering. By stacking multiple representation layers, deep networks extract subtle structural patterns across order-book dynamics, multi-asset correlations, and volatility term structures.
Key applications of deep learning in market analysis include:
- Limit Order Book (LOB) Representation: Modeling microstructure order-flow toxicity and queue dynamics.
- Multi-Factor Alpha Synthesis: Combining hundreds of technical, fundamental, and alternative factors into unified alpha scores.
- Synthetic Scenario Generation: Deploying Generative Adversarial Networks (GANs) and Variational Autoencoders (VAEs) to simulate synthetic market crises.
4. Recurrent Neural Networks (RNNs, LSTMs, GRUs)
Financial market data is fundamentally sequential: current asset pricing depends heavily on sequential temporal dependencies and autoregressive momentum. Standard feedforward networks treat data points independently, failing to capture time-series memory.
Recurrent Neural Networks (RNNs) introduce internal feedback loops to retain memory of previous inputs. To resolve the vanishing gradient problem inherent in standard RNNs, quantitative practitioners deploy specialized gated architectures:
- Long Short-Term Memory (LSTM) Networks: Utilize input, forget, and output gates to retain long-term macroeconomic trends while filtering transitory noise.
- Gated Recurrent Units (GRUs): A computationally streamlined variant combining hidden states and reset gates, offering faster convergence on high-frequency tick data.
Empirical research published by the Bank for International Settlements (BIS) confirms that recurrent neural networks and random forest ensembles demonstrate measurable utility in forecasting financial stress indicators and identifying the macroeconomic drivers of asset-price volatility.
5. Natural Language Processing (NLP) and Large Language Models
A substantial volume of market-moving intelligence originates outside numerical price series. Financial markets generate petabytes of unstructured textual information every day, including regulatory SEC disclosures (10-K, 10-Q, 8-K filings), earnings conference call transcripts, central bank monetary policy statements, and breaking financial news wires.
Modern NLP pipelines deploy transformer architectures (such as FinBERT and domain-adapted LLMs) to process text within milliseconds. These models perform:
- Named Entity Recognition (NER): Mapping subsidiaries, executive leadership, and supply-chain partners mentioned across global filings.
- Semantic Topic Modeling: Identifying emerging corporate themes, such as supply-chain disruptions, pricing power changes, or capital expenditure revisions.
- Contextual Embeddings: Converting textual narratives into numerical vector representations that can be ingested directly by quantitative factor models.
6. Contextual Sentiment Analysis
Sentiment analysis quantifies the tone and emotional stance expressed in financial discourse. Rather than relying on simplistic bag-of-words keyword counts, modern sentiment models classify text across granular semantic spectra: positive, negative, neutral, or uncertain.
Crucially, institutional researchers do not treat raw sentiment scores as direct buy or sell signals. The market impact of financial disclosures is heavily contextual: an earnings announcement reporting 15% revenue growth may trigger an immediate stock selloff if consensus analyst expectations anticipated 20% growth. Sophisticated quantitative desks therefore evaluate narrative sentiment relative to pre-existing market consensus and valuation multiples.
7. Anomaly Detection and Market Surveillance
Unsupervised machine learning algorithms excel at identifying structural outliers without requiring predefined training labels. In market analysis, anomaly detection algorithms—such as Isolation Forests, One-Class Support Vector Machines (OC-SVM), and Autoencoder reconstruction loss models—continuously scan trading environments to detect:
- Unusual trading volume surges and dark-pool execution anomalies
- Implied volatility surface mispricings and term-structure dislocations
- Microstructure quote stuffing or potential market manipulation patterns
- Data feed corruptions, latency spikes, and exchange timestamp mismatches
8. Predictive Probabilistic Modeling
Rather than generating naive point forecasts (e.g., predicting that an index will close at an exact dollar figure), institutional quantitative analysis focuses on probabilistic modeling. Using Bayesian neural networks, Gaussian processes, and quantile regression, systems forecast entire probability distributions of future returns, tail risks, and maximum expected drawdowns.
Comparative Analysis of Advanced AI Techniques for Stock Market Analysis
Understanding the operational strengths and computational overhead of each methodology is essential for engineering resilient trading workflows.
| Technique / Architecture | Primary Financial Use Case | Key Technical Strength | Primary Limitation |
|---|---|---|---|
| Gradient Boosted Trees (XGBoost) | Tabular equity screening & factor models | Fast training, excellent on tabular data, high interpretability | Cannot model raw unstructured text or sequential tick dynamics |
| Recurrent Networks (LSTM/GRU) | Sequential time-series & volatility forecasting | Captures temporal dependencies and order-book momentum | Computationally intensive, prone to overfitting historical noise |
| Transformers & FinBERT | Earnings call & news sentiment extraction | Understands nuanced financial syntax and narrative context | High inference latency, requires substantial GPU infrastructure |
| Isolation Forests / Autoencoders | Market surveillance & anomaly detection | Unsupervised discovery of unexpected liquidity dislocations | Can generate false positives during unprecedented macro events |
Benefits of Deploying Advanced AI Techniques for Stock Market Analysis
When properly validated and governed, integrating these computational techniques delivers significant analytical advantages:
- Scalable Multi-Asset Ingestion: Evaluates millions of global securities, futures contracts, and options chains simultaneously.
- Capturing Non-Linear Market Dynamics: Uncovers subtle cross-asset correlation shifts that traditional linear regression fails to detect.
- Multi-Modal Data Fusion: Merges numerical tick streams with qualitative narrative disclosures into unified risk models.
- Continuous Automated Surveillance: Monitors market regimes 24/7 across global exchanges without emotional bias or fatigue.
- Streamlined Quantitative Research: Reduces manual feature engineering and backtesting overhead for financial analysts.
Critical Challenges and Model Failure Modes
Despite their capabilities, deploying advanced mathematical algorithms in live capital markets involves severe engineering and statistical risks.
1. Overfitting and the Curve-Fitting Fallacy
Deep neural networks with millions of parameters can easily memorize random market noise rather than authentic alpha signals. A model displaying spectacular backtested Sharpe ratios often experiences catastrophic drawdowns when exposed to live order flows.
2. Look-Ahead Bias and Data Leakage
Data leakage occurs when information from the future inadvertently contaminates the training dataset. Examples include normalizing prices using full-sample statistics, incorporating corporate earnings before their official release timestamp, or training on datasets that suffer from survivorship bias (excluding delisted or bankrupt equities).
3. Non-Stationarity and Regime Shifts
Physical systems operate under unchanging physical laws; financial markets, by contrast, are non-stationary adaptive environments. A deep learning model trained during a sustained quantitative easing regime will fail when macroeconomic conditions transition abruptly to rapid rate hikes or geopolitical trade conflicts.
4. The Explainability and Black-Box Barrier
Complex deep learning architectures cannot easily articulate the mathematical rationale behind their predictions. In institutional finance, opacity creates significant compliance hurdles with risk officers and regulatory bodies.
How Advanced AI Models Should Be Validated
To prevent costly algorithmic failures, quantitative engineering teams must enforce a rigorous, non-negotiable validation lifecycle:
Historical Ingestion → Strict Out-of-Sample Split → Purged Walk-Forward Backtesting → Synthetic Stress Testing → Controlled Paper Deployment → Real-Time Drift Monitoring
Quantitative models should never be optimized purely to achieve attractive historical backtests. Testing frameworks must incorporate combinatorial purged cross-validation (CPCV) and historical regime simulation (such as the 2008 global financial crisis and 2020 liquidity shock) to evaluate structural resilience under adverse market conditions.
Furthermore, institutions can structure their machine learning governance around the NIST AI Risk Management Framework, applying the four core pillars of Govern, Map, Measure, and Manage across every stage of the model lifecycle.
For organizations seeking to design scalable automated data ingestion pipelines and production-grade quantitative workflows, exploring our specialized HuAI Content workflow automation services provides proven architectural guidance.
Why Human Expertise Remains Indispensable
No matter how sophisticated an algorithm becomes, computational models do not possess contextual judgment or strategic foresight. Human quantitative analysts and portfolio managers provide essential capabilities:
- Evaluating macroeconomic regimes and geopolitical shifts outside historical data distributions
- Interpreting corporate governance, executive credibility, and strategic business pivots
- Setting institutional risk budgets, leverage caps, and capital preservation mandates
- Deciding when to override, retrain, or decommission degrading algorithmic strategies
The most resilient investment models do not replace human judgment with autonomous machines; they empower experienced investment professionals with superior computational intelligence.
Conclusion
Advanced AI techniques for stock market analysis—from gradient-boosted trees and deep neural networks to sequential LSTMs and transformer-based sentiment models—have revolutionized the speed, depth, and scalability of equity research. However, computational sophistication should never be mistaken for market certainty.
Sustainable success in quantitative finance depends on high-quality data engineering, disciplined out-of-sample validation, sound risk governance, and vigilant human oversight. For the broader strategic framework of how these technical models integrate into institutional execution and portfolio management, read our foundational pillar article on The Rise of AI in Stock Trading: How Machine Learning Is Changing Investment Strategies.
To explore how these capabilities are deployed in daily market research, review our companion analysis on How AI Is Used in Stock Market Analysis and Trading, or examine ethical safeguards in The Ethical Implications of AI-Driven Stock Trading.
For additional technical guides and enterprise automation tutorials, visit the HuAI Content blog.
Frequently Asked Questions (FAQ)
What are the most effective AI techniques for stock market analysis?
The most effective AI techniques for stock market analysis depend on the specific data modality. Gradient-boosted decision trees (XGBoost, LightGBM) excel at tabular feature modeling, Recurrent Neural Networks (LSTMs, GRUs) model sequential price time series, and transformer models (FinBERT) analyze unstructured financial text and earnings transcripts.
Can deep learning reliably predict stock market prices?
No model can guarantee accurate stock price forecasts. Deep learning models produce probabilistic estimations based on historical data patterns. Because financial markets are non-stationary and subject to unexpected macroeconomic and geopolitical shocks, forecasts remain inherently probabilistic.
How does natural language processing enhance stock market research?
Natural language processing extracts quantitative sentiment scores, identifies executive tone shifts, and flags material corporate events from vast unstructured textual sources, including SEC 10-K filings, earnings conference call transcripts, and real-time news wires.
What is the biggest operational risk in financial deep learning?
The primary operational hazard is model overfitting combined with market regime shift. A complex neural network can easily memorize historical market noise, producing impressive backtests that degrade rapidly when deployed in live trading environments.
Why is human oversight necessary when using AI in finance?
Human analysts provide critical qualitative context, evaluate unprecedented geopolitical dislocations, enforce ethical risk limits, and maintain legal accountability for investment decisions that automated algorithms cannot assess.
Editorial Disclaimer: This article is published exclusively for educational, technical, and informational purposes and does not constitute financial, investment, legal, or trading advice.