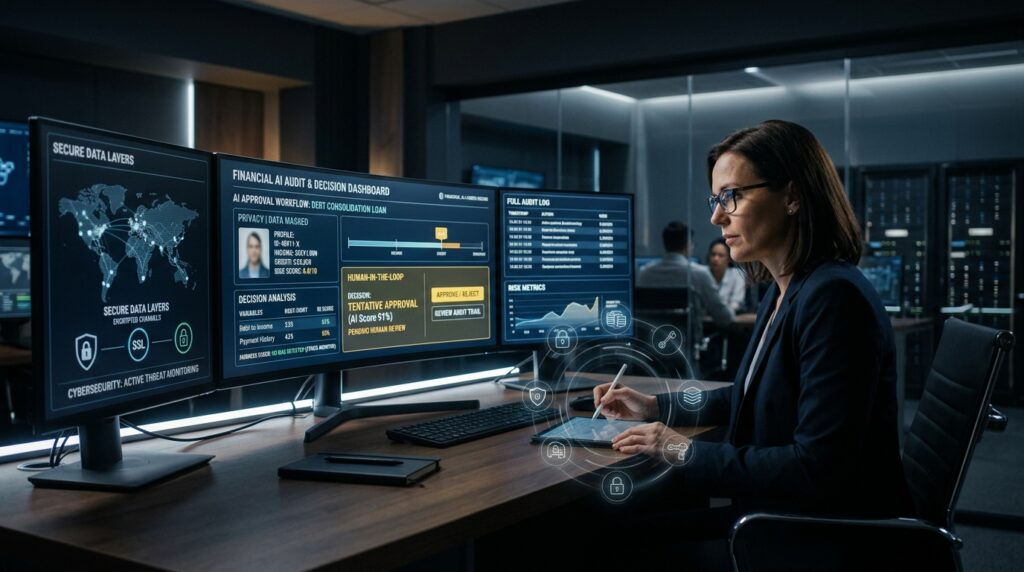
Artificial intelligence provides unprecedented velocity, operational efficiency, and scalable decision-making across modern financial services. However, deploying machine learning in banking and capital markets operates in a high-stakes domain where algorithmic errors directly impact people’s capital, credit access, and personal livelihood. Understanding AI ethics in FinTech has therefore transitioned from a philosophical debate into an essential operational requirement.
Responsible financial technology is not merely a question of mathematical model accuracy; it is fundamentally a question of institutional trust, consumer privacy, cybersecurity resilience, and legal accountability. As financial algorithms take on larger roles in credit underwriting, fraud detection, and automated trading, financial institutions must build rigorous ethical guardrails into every layer of their software infrastructure.
This comprehensive guide examines the critical dimensions of AI ethics in FinTech, outlining core operational vulnerabilities, regulatory standards, and practical frameworks for building transparent, trustworthy financial systems.
What Are the Ethical Risks of AI in FinTech?
As examined in our comprehensive analysis of AI applications in FinTech, automated fraud detection, alternative credit scoring, and digital banking workflows unlock substantial efficiency. However, deploying machine learning in live production environments requires a systematic understanding of operational and ethical failure modes.
1. Client Data Privacy and Data Exploitation
Financial technology platforms process vast volumes of highly sensitive personal and organizational data, including:
- Personally Identifiable Information (PII) and Know-Your-Customer (KYC) records
- Real-time transaction histories and merchant spending habits
- Account balances, credit card numbers, and wealth management portfolios
- Mobile telemetry, biometric authentication fingerprints, and device geolocations
- Proprietary business telemetry and payroll disclosures
Machine learning models require immense training corpora, creating serious risks around unauthorized data harvesting, unauthorized secondary data reuse, and third-party data broker monetization. Financial institutions must maintain strict data minimization protocols, zero-trust role-based access, and cryptographic encryption both at rest and in transit.
Analysis published in 2026 by the Bank for International Settlements (BIS) explicitly identifies data privacy, data quality, and secure data handling as primary supervisory concerns and structural barriers to responsible financial AI adoption.
2. Cybersecurity and Supply-Chain Risk Amplification
While artificial intelligence enhances cyber defense by detecting anomalous network intrusions in real time, it also expands the attack surface and velocity of cyber risks. FinTech systems rely on complex distributed software stacks: cloud compute platforms, third-party model APIs, open-source libraries, and external data feeds.
A single vulnerability or model poisoning exploit in a shared third-party dependency can propagate systemic contagion across payment gateways and banking networks. Research from the International Monetary Fund (IMF) highlights that AI significantly accelerates the speed and scale at which cyber shocks transmit through interconnected digital infrastructure, making operational resilience a critical component of AI ethics in FinTech.
3. Algorithmic Bias and Systemic Financial Exclusion
Machine learning algorithms formulate predictive hypotheses entirely from historical data distributions. If historical lending datasets reflect systemic societal inequities, redlining, or credit-market discrimination, algorithms will mathematically reproduce and amplify those patterns under the guise of objective calculation.
This danger is especially acute across automated credit scoring, small-business lending, and insurance pricing. A model that achieves high statistical accuracy may systematically assign lower credit limits to underrepresented demographics due to correlated proxy variables (such as postal codes or educational credentials). Responsible engineering requires continuous disparate impact audits and demographic parity testing.
4. The Explainability Barrier: Why AI Ethics in FinTech Requires Transparency
Complex deep neural networks and gradient-boosted ensembles are frequently opaque. When an automated credit algorithm denies a mortgage application or freezes a merchant’s working-capital facility, adverse-action regulations legally require the financial institution to articulate the exact, actionable reasons for the rejection.
Lack of explainability frustrates customers, complicates external regulatory audits, and prevents internal risk committees from diagnosing why a model failed during unprecedented market conditions. Financial institutions must implement Explainable AI (XAI) frameworks—such as SHAP and LIME—to ensure model outputs remain interpretable.
Similar governance dilemmas exist across algorithmic trading and execution platforms, where opaque decisions can trigger market microstructure instability, as analyzed in our review of ethical implications of AI-driven stock trading.
5. Unambiguous Institutional Accountability
When an algorithmic system executes an incorrect trade, misallocates portfolio risk, or incorrectly denies a legitimate claim, legal and ethical liability remains strictly with human managers and corporate leadership. Deflecting accountability with the excuse that “the neural network made an autonomous decision” represents a catastrophic corporate governance failure.
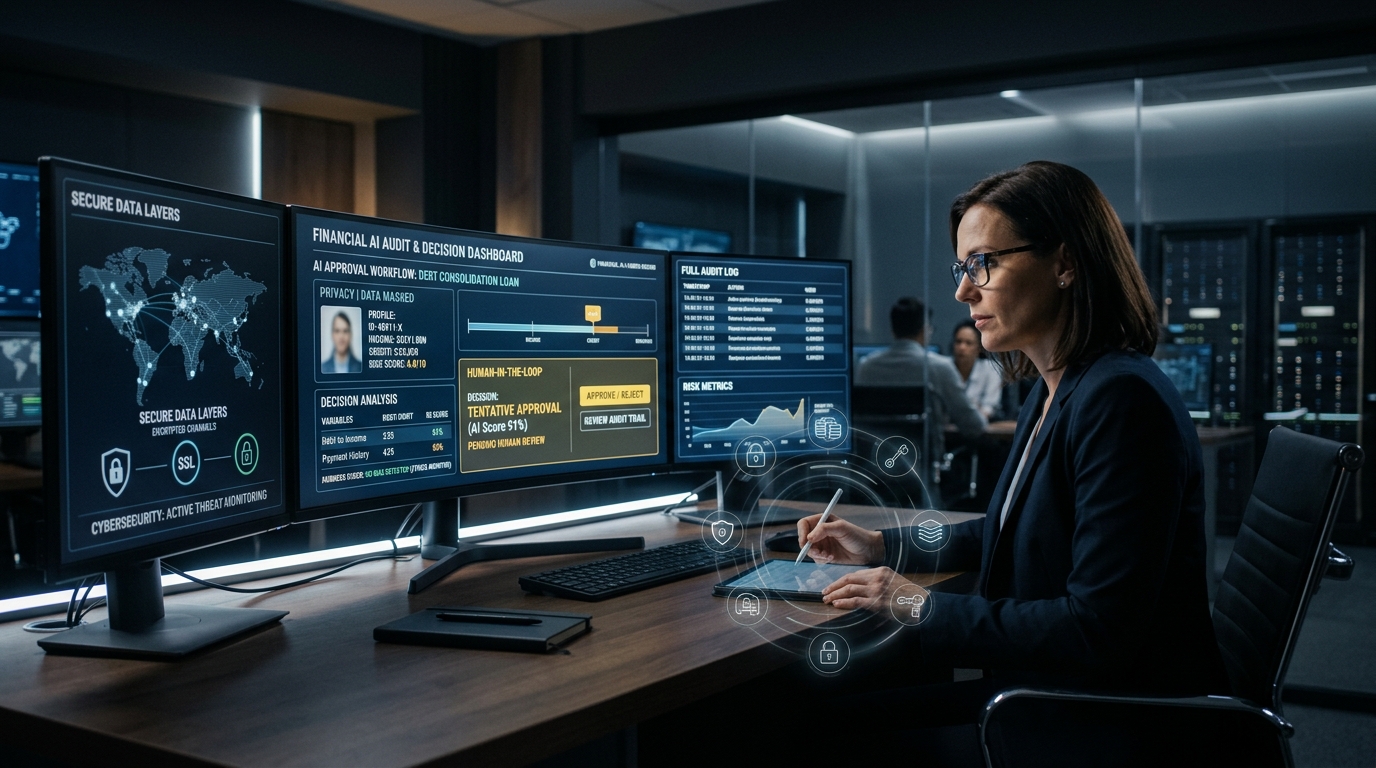
Institutions must establish clear ownership lines: who authorized the model, who verified the data hygiene, who oversees live execution thresholds, and who possesses the authority to deploy an emergency kill-switch.
6. Third-Party Vendor and Cloud Concentration Dependencies
Most digital banks and FinTech startups do not train foundational models from scratch; they integrate external cloud infrastructure and commercial AI APIs. As hundreds of financial applications consolidate around a handful of dominant cloud providers and model vendors, any infrastructure outage or vendor-level security flaw becomes a systemic financial stability event.
These governance questions become even more important as FinTech moves from traditional machine learning toward generative and agentic AI-driven FinTech innovations.
Will AI Replace Financial Professionals?
The institutional reality of financial technology is not a total replacement of human professionals, but a fundamental transformation of job responsibilities. Artificial intelligence excels at executing high-velocity, repetitive tasks with mathematical consistency:
- Normalizing messy transaction streams and extracting text from SEC filings
- Automating initial customer service triage and routing routine account inquiries
- Screening transaction logs for AML and OFAC sanctions violations
- Calculating real-time portfolio risk exposures and variance metrics
However, experienced human professionals remain irreplaceable for contextual strategic judgment, corporate client negotiations, ethical oversight, crisis navigation, and fiduciary accountability. The most resilient FinTech organizations do not replace their workforce with autonomous software; they equip experienced professionals with superior computational intelligence.
Operationalizing AI Ethics in FinTech to Build Consumer Trust
Building sustainable user trust requires FinTech organizations to translate ethical values into operational engineering practices:
| Trust Pillar | Engineering & Operational Action | Customer & Regulatory Outcome |
|---|---|---|
| Pre-Deployment Risk Audits | Conduct structured algorithmic impact assessments before live rollout | Identifies potential harms and failure modes prior to consumer exposure |
| Data Minimization & Privacy | Enforce strict encryption, tokenization, and privacy-preserving federated learning | Prevents catastrophic customer data leaks and ensures regulatory compliance |
| Continuous Bias Auditing | Audit credit models across demographic cohorts using statistical parity tests | Guarantees fair lending and prevents discriminatory credit denials |
| Performance & Drift Monitoring | Track Kolmogorov-Smirnov distance and concept drift across macro cycles | Detects model degradation before live financial losses occur |
| Human Escalation Gateways | Provide immediate, frictionless routes to human support when algorithms fail | Maintains user dignity, empathy, and rapid error rectification |
Regulatory Landscape and AI Governance Mandates
Financial regulatory authorities worldwide are actively establishing mandatory governance frameworks for artificial intelligence. In India, the Securities and Exchange Board of India (SEBI) issued an updated Master Circular for Investment Advisers that establishes binding legal obligations:
- Fiduciary Responsibility: Financial advisers utilizing AI tools remain personally and legally liable for the security, confidentiality, and integrity of client data.
- Advice Integrity: Registered entities retain complete legal accountability for any advice generated or augmented by automated algorithms.
- Mandatory Disclosure: Advisers are legally mandated to disclose the exact scope, nature, and extent of AI utilization directly to their clients.
The regulatory precedent is unambiguous: utilizing an external AI vendor never transfers legal liability away from the financial institution.
A Practical Responsible-AI Framework
To implement comprehensive AI ethics in FinTech, institutions can adopt the structured four-tier lifecycle defined by the NIST AI Risk Management Framework:
GOVERN → MAP → MEASURE → MANAGE
- GOVERN: Establish institutional oversight boards, define ethical risk tolerances, and institute clear individual human accountability.
- MAP: Identify data sources, document third-party dependencies, map model assumptions, and evaluate potential consumer harms.
- MEASURE: Conduct quantitative bias audits, stress-test security resilience, track explainability metrics, and evaluate out-of-sample stability.
- MANAGE: Deploy real-time automated risk gates, maintain audit logs, enforce emergency kill-switches, and establish human escalation pathways.
For organizations looking to deploy automated data pipelines that incorporate production-grade compliance guardrails, our specialized HuAI Content workflow automation services provide tailored infrastructure.
Conclusion
Artificial intelligence holds immense promise for expanding financial inclusion, streamlining operations, and delivering intuitive banking experiences. However, institutional trust cannot be automated.
Sustainable innovation in the modern FinTech sector requires organizations to treat AI ethics in FinTech as a core engineering discipline. By combining technical excellence with rigorous data privacy, cybersecurity resilience, algorithmic fairness, explainability, and unwavering human oversight, forward-thinking institutions can build financial services that are both high-performing and deeply trustworthy.
For the broader applications of AI across financial technology, explore our pillar article on AI in financial services. You can also explore our technical analyses and tutorials across the HuAI Content blog.
Frequently Asked Questions (FAQ)
What are the primary ethical concerns surrounding AI ethics in FinTech?
The primary concerns in AI ethics in FinTech include client data privacy violations, algorithmic bias in lending decisions, lack of model explainability (black-box decisions), third-party technology concentration, and the absence of clear human accountability.
How does artificial intelligence introduce bias into financial decisions?
AI models learn from historical financial datasets. If those datasets contain historical disparities, redlining, or socio-economic exclusions, the algorithm will mathematically identify and reinforce those patterns, resulting in unfair credit denials or predatory pricing.
Why is explainability essential for ethical financial algorithms?
Explainability allows risk officers, auditors, and regulators to understand the mathematical drivers behind automated decisions. It ensures that credit denials can be legally justified under adverse-action statutes and prevents opaque, discriminatory algorithmic outcomes.
Does using external AI APIs reduce an institution’s regulatory liability?
No. Financial regulatory bodies, including SEBI and the BIS, strictly mandate that regulated financial institutions retain full fiduciary, legal, and operational responsibility for automated systems, regardless of whether models are built internally or licensed from third-party vendors.
How can consumers verify if a financial institution uses ethical AI?
Consumers should review the institution’s transparent AI disclosures, verify adherence to data privacy standards (such as GDPR or regional financial privacy laws), and confirm the availability of clear human escalation channels for disputing automated decisions.
Editorial Disclaimer: This article is published exclusively for educational, technical, and informational purposes and does not constitute legal, financial, investment, or regulatory advice.